How do mortgage terms affect monthly payments?
Want to slash your monthly mortgage payment? Change the terms you pick, not your lifestyle.
Why mortgage terms matter right now
Mortgage terms are not fluff. They set your interest rate, loan length, and how fast you pay down principal. Those three things alone decide what hits your bank account every month. Understand them and you control your cash flow.
The three term levers that change your monthly payment
- Interest rate: Higher rate = higher payment. Simple.
- Loan term (amortization): Longer term = lower monthly payment, more interest paid over life of loan.
- Type of rate: Fixed-rate gives stability. Adjustable-rate can start lower but can rise.
Real-world comparisons — numbers that prove the point
Example 1 — Same loan, different rates
- Loan: $400,000, 30-year amortization
- At 3.00% fixed → Monthly ≈ $1,686
- At 4.00% fixed → Monthly ≈ $1,909 A 1% rate increase costs about $223 more each month on $400k.
Example 2 — Same rate, different terms
- Loan: $400,000 at 3.00%
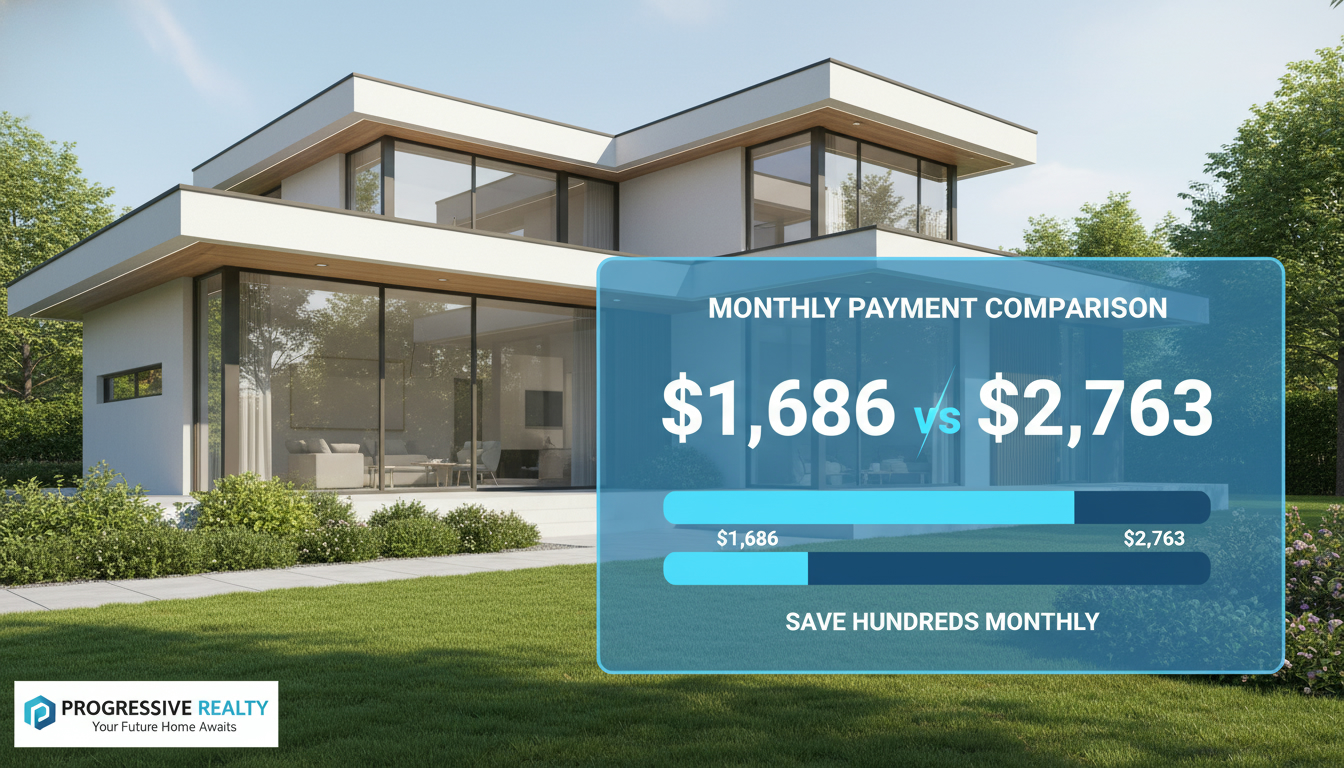
- 30-year → Monthly ≈ $1,686
- 15-year → Monthly ≈ $2,763 Cut the term in half and your payment jumps by about $1,077. You pay less interest total, but your monthly cash flow tightens.
How to use this knowledge — actionable moves
- Run numbers before you decide. Use a mortgage calculator to test rate and term combinations.
- If cash flow is tight, pick a longer amortization to lower monthly payment. Accept higher lifetime interest if needed.
- If you want to pay less interest long-term, choose a shorter term or make extra principal payments.
- Consider fixed vs adjustable carefully: fixed protects against rate spikes; adjustable can save money short-term.
- Refinance when rates drop and your break-even math works. Include closing costs in your calculation.
- Use bi-weekly payments or one extra payment a year to shave years off your mortgage and reduce total interest.
Quick checklist before you sign
- Compare interest rates across lenders.
- Compute monthly payment for at least three term/rate scenarios.
- Ask about penalties for prepayment and refinancing costs.
- Confirm whether taxes and insurance are included in your quoted monthly payment.
Final word — pick the terms that match your goals
If your goal is lower monthly cash flow, extend the amortization or hunt for a lower rate. If your goal is paying the loan off fast and saving interest, shorten the term or make extra payments. Both paths work. Use the numbers above to decide.
For expert guidance and mortgage calculations tailored to your situation, contact Tony Sousa — Local Financing & Mortgages expert. [email protected] | 416-477-2620 | https://www.sousasells.ca
Featured Real Estate Listings
Browse current properties available right now. Click any listing to view photos, floor plans, or schedule a private tour.


