How Much Household Income Do You Need to Buy a Milton Townhouse in 2026?
First-time buyer edition: local Milton market data, the mortgage stress test, and what an $800,000 townhouse actually costs to carry.
“We earn a combined $120,000 a year, we have solid credit, and we both work full-time. Why are we getting priced out of townhouses in Milton?”
I hear this exact question every week from first-time home buyers.
The challenge isn't just property appreciation. It’s the qualification math behind the Canadian mortgage stress test.
In Milton, the benchmark home price sits near $877,000, while the average sold price across all townhouse styles (freehold and condominium) trends around $787,000 to $800,000. Milton continues to attract buyers priced out of Toronto, Mississauga, and Oakville thanks to its family-friendly master-planned communities and GO Transit access.
However, when you calculate the financing under current lending regulations, the gross annual income required to purchase an entry-level townhome is often significantly higher than buyers anticipate.
The $800,000 Milton Townhouse Example
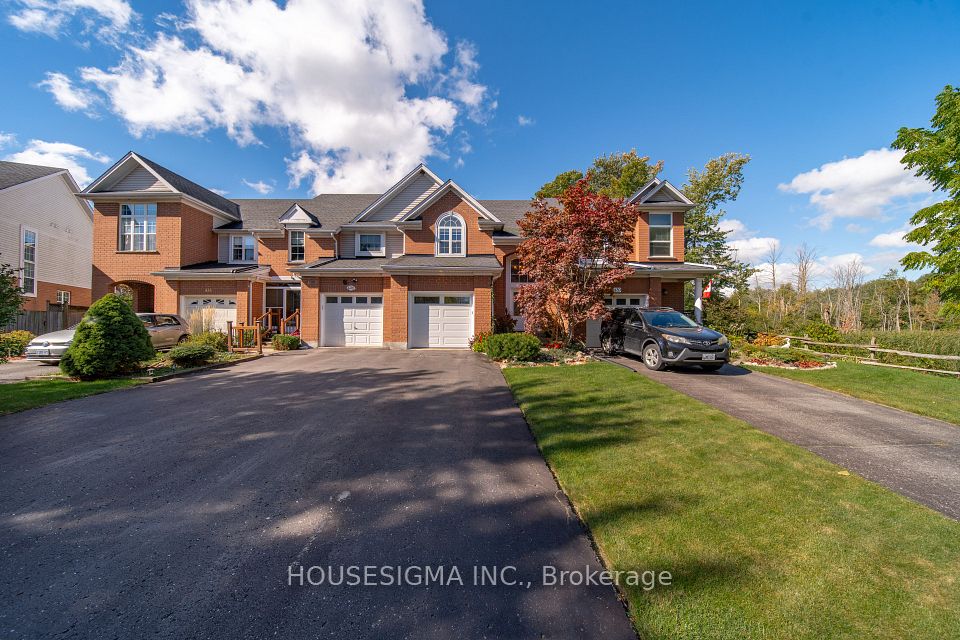
Let’s look at a typical 3-bedroom townhouse in popular Milton neighbourhoods like Clarke, Beaty, Willmott, or Coates.
- Purchase price: $800,000
- Down payment (20%): $160,000
- Base mortgage: $640,000
- Amortization: 25 years
- Illustrative qualifying rate: 5.25% (OSFI minimum floor / stress test rate)
- Property taxes: $420/month
- Heating / Utilities: $120/month
- Condo / Common Elements fee (POTL): $200/month
Note on Qualification: Under OSFI guidelines, uninsured mortgages must qualify at the contract rate plus 2% or 5.25%, whichever is greater. Lenders typically factor 50% of monthly maintenance/POTL fees into the debt service ratio.
At a 5.25% qualifying rate, a $640,000 mortgage produces an illustrative monthly payment of approximately $3,835.
Qualifying Monthly Housing Cost Breakdown
| Cost Component | Monthly Amount |
|---|---|
| Mortgage Payment (at 5.25% qualifying rate) | $3,835 |
| Property Taxes (Milton estimated rate) | $420 |
| Heating Costs | $120 |
| 50% of $200 Maintenance/POTL Fee | $100 |
| Total Monthly Qualifying Housing Cost | $4,475/month |
That represents approximately $53,700 per year in total qualifying shelter costs.
Applying a standard 32% Gross Debt Service (GDS) threshold, you need an estimated gross household income of:
$168,000 per year
That works out to roughly $84,000 per year per earner for a dual-income household.
What If You Have Less Than 20% Down?
Saving $160,000 while paying rent in the GTA is one of the hardest hurdles for first-time buyers.
Putting less than 20% down is common, but it triggers CMHC mortgage loan insurance (or Sagen/Canada Guaranty), which is added directly to the total principal borrowed.
Scenario Comparison: $800,000 Purchase Price
| Metric | 20% Down Payment | 10% Down Payment | Minimum Down Payment |
|---|---|---|---|
| Down Payment Amount | $160,000 | $80,000 | $55,000 |
| Mortgage Insurance Premium | $0 (0%) | ~$22,320 (3.1%) | ~$29,800 (4.0%) |
| Total Financed Mortgage | $640,000 | ~$742,320 | ~$774,800 |
| Monthly Stress-Test Payment | ~$3,835 | ~$4,445 | ~$4,640 |
| Total Monthly Carrying (GDS) | ~$4,475 | ~$5,085 | ~$5,280 |
| Required Household Income | ~$168,000/yr | ~$191,000/yr | ~$198,000/yr |
(Minimum down payment calculation: 5% on the first $500,000 = $25,000, plus 10% on the remaining $300,000 = $30,000, totaling $55,000.)
The Core Takeaway
A smaller down payment lowers the cash barrier to entry, but it expands your loan size and insurance overhead. To qualify for that larger loan under the stress test, your household income must jump by nearly $30,000 per year.
How to Assess Your Real Purchasing Power
To avoid falling in love with a property you cannot finance, work backward from your finances rather than forward from listing photos:
- Audit Gross Incomes: Document stable base salaries, verifiable self-employment income, or consistent bonus history.
- Calculate Non-Housing Liabilities: Outstanding car loans, student debt, and credit card balances count directly against your Total Debt Service (TDS) limit (typically capped around 40% to 44%).
- Distinguish Freehold from Condo Townhomes: Freehold townhomes have no maintenance fees, meaning 100% of your debt capacity goes directly toward servicing the mortgage principal.
- Account for Closing Costs: Budget 1.5% to 2% of the purchase price for Ontario Land Transfer Tax (less first-time buyer rebates), legal disbursements, and title insurance.
Strategic Alternatives for Milton Buyers
If your current household earnings do not align with an $800,000 purchase price, consider these adjustments:
- Target 2-Bedroom or Stacked Townhomes: Units in developments along Derry Road, Main Street, or Scott offer purchase prices between $580,000 and $680,000, reducing income requirements to ~$130,000–$145,000.
- Explore Adjacent Halton & Wellington Markets: Broaden your radar to Georgetown (Halton Hills) or East Guelph for varied price-per-square-foot ratios.
- Optimize Non-Mortgage Debt First: Paying off a $500/month car loan often frees up more borrowing capacity than saving an extra $10,000 in cash.
Tony Sousa, Realtor
HouseSigma Ltd. Brokerage
416-477-2620
Mortgage calculations provided above are illustrative estimates for planning purposes only and do not constitute a financial commitment or formal pre-approval. Qualification criteria, insurance rates, and lender underwriting parameters vary based on individual credit history and property type.
Homes For Sale in Milton Under $800,000
Browse current properties available right now. Click any listing to view photos, floor plans, or schedule a private tour.